










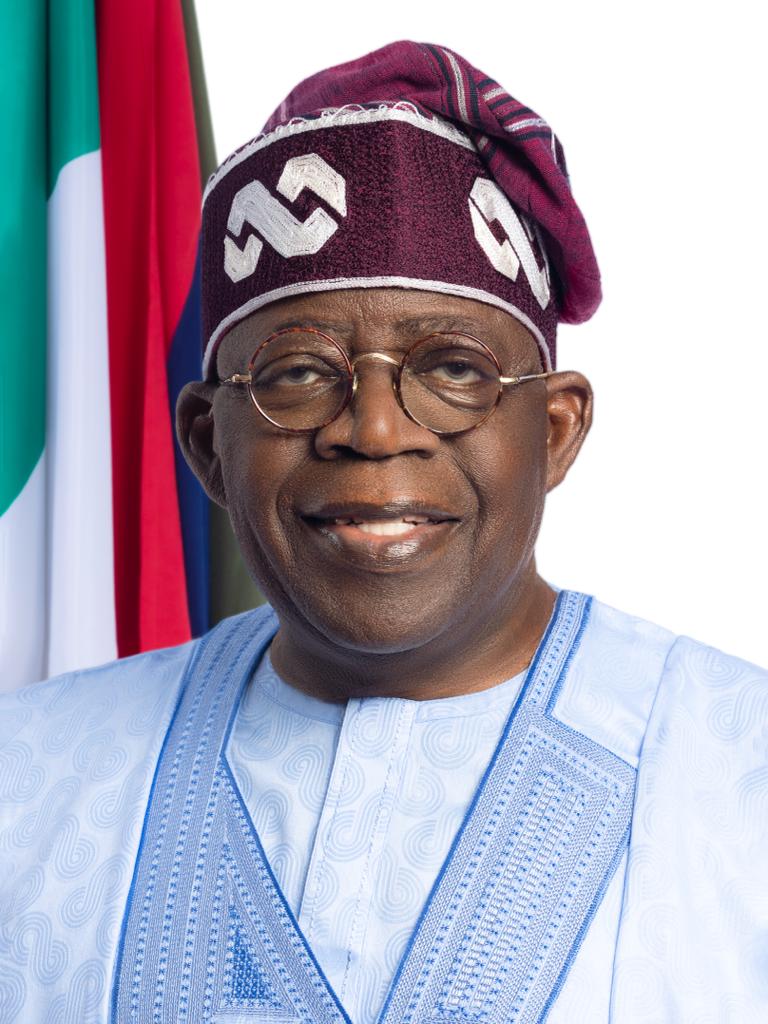
President Bola Tinubu has requested Senate approval for a fresh external borrowing of $7.7bn, equivalent to approximately ₦10.79trn, to part-finance the Federal Government’s 2026 budget deficit. The request replaces an earlier proposal seeking approval for $20.52bn and €1.045bn in external borrowing. The proposed borrowing forms part of the ₦29.2trn new borrowing provision in the 2026 Appropriation Act, which is intended to finance a projected budget deficit of approximately ₦31.4trn. Under the financing plan, the government intends to raise ₦18.4trn from the domestic market, while the remaining ₦10.79trn will be sourced externally. The President stated that the funds would be raised through a combination of financing options, including multilateral and bilateral loans, commercial facilities and Eurobond issuance. However, greater emphasis will be placed on Eurobonds due to their relatively faster execution and ability to raise substantial funding. The proposed borrowing comes amid concerns over Nigeria’s rising public debt and debt-servicing obligations, with increased external financing potentially adding to foreign-currency repayment pressures. For the Eurobond market, the government’s preference for international bond issuance could signal a potential new supply of Nigerian sovereign debt, although the timing, size and pricing of any issuance remain subject to market conditions.
Money Market
System liquidity saw an increasing trend throughout the trading week, opening at ₦7.38 trillion on Monday and closing at ₦5.78 trillion driven by OMO auction settlement. Week-on-week, the Nigerian Overnight Financing Rate (NOFR) held steady to close at 20.00%, while the Overnight (OVN) rates declined by 18bps to close at 20.20%.
We expect rate to continue to hover around this level.
Treasury Bills Market
The Treasury Bills market traded on an active note this week, driven by OMO and NTB auctions. The week began with investors positioning cautiously ahead of Wednesday’s ₦800bn NTB auction, while demand in the OMO segment remained concentrated in December papers, with bids on the 29-Dec bill around 18.55%. Activity picked up following the inflow OMO maturities, which prompted the CBN to conduct an OMO auction offering ₦1.50trn across various tenors. The auction attracted ₦3.51trn in subscriptions, with ₦2.94trn allotted. As the week progressed, attention shifted to the NTB auction, where subscriptions reached ₦2.04trn, while the DMO allotted ₦509.40bn. Stop rates remained unchanged across all three tenors at 15.40%, 15.79% and 15.80%, respectively, as the DMO maintained its measured approach to borrowing despite the strong demand. Secondary market activity remained relatively subdued after the auction, with the newly issued 4-Nov bill quoted around 15.70%/15.55%. Towards the end of the week, the Apex bank returned with another ₦1.50trn OMO, which attracted ₦5.73trn in subscriptions and allotting ₦2.72trn. The 361-day paper accounted for the bulk of the allotment at ₦1.99trn, which cleared at 15.74%. Post-auction activity remained active, with the newly issued 2-Nov OMO paper quoted at 15.60%/15.50%, with bids seen at 15.55% as the week drew to a close.
Looking ahead, we expect an active session supported by the inflow of OMO maturities.
FGN Bond Market
The FGN Bond market traded on a positive note this week, supported by mild buying interest across the mid-to-long end of the curve. The week started on a slightly positive note, with demand more evident in off-the-run maturities, particularly the 2033 maturity where yields declined from 16.90%/16.75% to 16.85%/16.70%. The 2038 maturity also attracted bids, with yields moving below the 17.00% handle. As the week progressed, activity remained cautious ahead of the NTB auction, although interest persisted in the 2033s, 2034s and 2038s, with buyers maintaining a selective approach. Following the NTB auction, where the DMO undersold for the third consecutive time, buying sentiment improved as investors increased expectations of a measured borrowing approach at the upcoming FGN bond auction. This encouraged increased demand from local investors, particularly in the 2038 maturity, which repriced lower to 16.85%/16.70%, with trades consummated around 16.80%. Interest also extended to off-the-run maturities, with trades executed in the 2031 and 2033 maturities at 16.55% and 16.70%, respectively. By week-end, the market maintained a firm tone, although demand was met by selling interest, as the 2038 maturity closed the week quoted around 16.75%. Week-on-week, the average benchmark yield declined by 5bps to close at 16.18%.
Looking ahead, we expect this positive sentiment to persist in the near term as investors position for the FGN bond auction.
FGN Eurobond Market
The Eurobond market traded on a mildly positive note this week, as sentiment was largely driven by the U.S midterms elections. The week started on a strong note which was supported by renewed diplomatic efforts, with Iranian negotiators holding talks with Qatari mediators in Doha and reports that Iran’s Supreme Leader had authorized the government to pursue negotiations. However, optimism was interrupted by renewed U.S. military attacks on Iran’s Qeshm Island and Tehran’s warning of retaliatory action, which raised concerns over further escalation. As the week progressed, sentiment improved following the U.S. midterm elections, where Democrats secured control of both chambers of Congress, limiting President Trump’s ability to advance his policy agenda. Investors took some comfort from the possibility that the Democrat’s victory could reduce further military escalation, helping to reduce the geopolitical risk in the market. However, the positive momentum was briefly interrupted by the Bank of England’s 25bps rate hike, which prompted investors to reassess the global rate outlook and take some profits across the curve. Towards the end of the week, the market was on a negative note as investors assessed the possibility of further U.S. action against Iran following the elections. Meanwhile, NFP Actual came in at 165k vs Previous 29k, pointing to continued resilience in the labour market and adding to uncertainty around the outlook for interest rate. Week-on-Week, the average benchmark yield declined by 16bps to close at 7.00%.
We expect market direction to be driven by evolving geopolitical developments, CPI and PPI data.
Currency Market
The value of the Naira to the dollar depreciated by 0.04% week on week to close at ₦1,346.79/$ at the Nigerian Foreign Exchange Market Window (NFEM).
Equities Market
The local bourse ended the day with the benchmark NGX All-Share Index (ASI) decreasing by 0.33% to close at 248,877.2 points while market capitalisation also decreased to close at N162.91 trillion. Market breadth was positive at 1.07x. Trading activity was significantly active on the day, with the volume of shares traded decreasing by 3.36% to 369.92 million units, while total value of shares traded decreased by 11.88% to ₦26.03 billion.
Reflecting the week’s performance, the NGX All-Share Index depreciated by 2.13%, as gains in HONYFLOUR (+30.82%), TRANSPOWER (+23.37%), and ETRANZACT (+14.42%) were offset by declines in VITAFOAM (-18.96%), SOVRENINS (-17.02%), and ETERNA (-15.79%).
Overall, the NGX has posted a year-to-date gain of 59.93%. Other notable indices are the NGX Top 30 Index (-0.40%; -2.10% 1WK; 61.67% YTD), NGX Banking Index (-0.77%; -3.71% 1WK; 56.34% YTD), NGX Oil & Gas Index (0.12%; -3.78% 1WK; +119.43% YTD), and NGX Insurance Index (+3.34%; -0.99% 1WK; -13.67% YTD).